André Kostolany: Europe’s Great Speculator and His Market Wisdom
Born in Budapest, he made and lost fortunes in Paris and New York and became famous in Germany for his wit. André Kostolany left some of the most quoted lessons in investing, including the advice to buy shares and take sleeping pills.
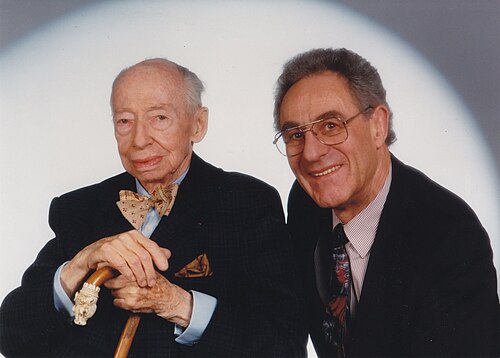
Photo: Bennys Buidl Fabrik · CC BY-SA 4.0, via Wikimedia Commons
A speculator from Budapest
André Kostolany was born in Budapest on 9 February 1906. He studied philosophy and art history, but in 1924 his father sent him to Paris to learn the stockbroking trade. He became a speculator and arbitrageur, and made his first fortune by betting on falling prices as markets collapsed from late 1929. He also lost heavily more than once on bets that went wrong, and his later advice is full of warnings about speculating with borrowed or needed money.
When German troops occupied France in 1940 he fled to New York, where from 1941 to 1950 he ran a financing company. From 1950 he lived mainly in Paris again, with an office in Munich and a holiday home on the Côte d’Azur.
Betting on Germany
After the Second World War Kostolany invested heavily in West Germany’s reconstruction, at a time when many investors doubted the country would recover. The bet paid off as Germany’s post-war boom took hold, and the country became his main audience. For decades he wrote for the monthly business magazine Capital, 414 articles in all, gave seminars and appeared on television, becoming Germany’s best-known voice on the stock market. His 13 books, including “Kostolanys Börsenpsychologie” (1991) and “Die Kunst über Geld nachzudenken”, published in 2000 after his death, sold more than 3 million copies.
The man and the dog
His most famous image explains the difference between the economy and the stock market. A man walks his dog. The man moves slowly and steadily forward, while the dog runs ahead, falls behind and dashes off in all directions, but in the end both arrive at the same place. The economy is the man; the stock market is the dog. In the short run prices follow the mood of the crowd; in the long run they follow the real economy.
Shaky hands and firm ones
Kostolany divided investors into two groups. People with “shaky hands” buy when everyone is excited and sell when they are frightened. People with firm hands have four things: money they don’t need, their own ideas, patience and luck. In his view prices rise when shares pass from shaky hands into firm ones, and fall when they pass back. His “egg” model describes the cycle: after a fall comes a correction, then a phase in which prices rise with the news, then an exaggeration phase of euphoria, followed by the same three phases on the way down. The practical message is to buy in the correction phase, when pessimism is widest, and to be cautious in the exaggeration phase, when everyone is euphoric.
Several of his lines are still quoted in almost every market cycle:
- “Anything is possible on the stock market. Even the opposite.”
- “Stock market profits are compensation for pain and suffering. First comes pain, then comes money.”
- “I can’t tell you how to get rich quickly; I can only tell you how to get poor quickly: by trying to get rich quickly.”
- “Who does not own shares when their prices drop will not own shares when prices soar.”
“Buy stocks, take sleeping pills for 20 years, and stop looking at the papers. After many years, you will see: you’ll be rich.” — André Kostolany
What still applies today
Kostolany died in Paris on 14 September 1999, aged 93. Much of his advice fits modern index investing remarkably well: separate short-term noise from long-term growth, invest only money you can leave alone, don’t borrow to speculate, and remember that the hardest part of investing is controlling your own nerves. He was a speculator who ended up recommending patience, which may be the most convincing endorsement patience has ever had. This profile is general education, not investment advice.
Should you sell when the stock market crashes?
What history says about selling in a panic, and what to do instead.
This article is educational and general in nature. It isn’t personalized investment, tax, or legal advice — always weigh your own circumstances, or talk to a licensed professional, before making financial decisions.
Keep reading
Related guides on this topic.
 Legendary Investors
Jesse Livermore: Lessons From Wall Street's Original Speculator
Long before technical analysis had a name, a teenage "boy plunger" was reading tape and making — and losing — some of the largest fortunes Wall Street had ever seen.
Legendary InvestorsRaamdeo Agrawal: The Co-Founder of Motilal Oswal and His QGLP Approach to Investing
Raamdeo Agrawal arrived in Mumbai to study accountancy, co-founded Motilal Oswal and became one of India’s best-known long-term investors. His QGLP framework, the Hero Honda and Eicher stories, and the lessons for ordinary investors.
Legendary InvestorsNick Train: Britain’s Quality-Stock Investor, His 25-Year Record and His Rough Patch
Nick Train built one of Britain’s best long-term records by owning a handful of great brands and rarely selling. Then came five years of painful underperformance. His approach, his numbers, and what his rough patch teaches every investor.
Legendary InvestorsWalter Schloss: The Value Investor Who Beat the Market for 45 Years Without Meeting a CEO
Walter Schloss never went to university, worked from a small office and owned dozens of cheap, dull companies — and compounded his investors’ money at about 15% a year for nearly half a century. How he did it.
Legendary InvestorsLuiz Barsi Filho: Brazil’s “King of Dividends” and His Retirement Portfolio
From shoeshine boy in São Paulo to the largest individual investor on Brazil’s stock exchange, Luiz Barsi built his fortune by buying dividend-paying shares every month for decades and almost never selling.
Legendary InvestorsAshish Kacholia: India’s “Big Whale” of Small-Cap Investing
Ashish Kacholia started as a broker and analyst, co-founded Hungama with Rakesh Jhunjhunwala and became one of India’s most-watched small-cap investors. His story, his approach, what his portfolio looks like, and why copying it is harder than it seems.