Benjamin Graham: The Father of Value Investing
Long before Warren Buffett was a household name, his teacher wrote the book that gave value investing its name — and its most durable idea: margin of safety.
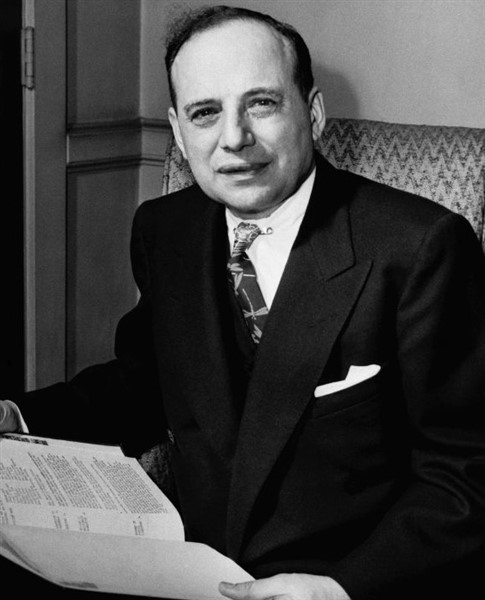
Photo: AnonymousUnknown author · Public domain, via Wikimedia Commons
A discipline born from a crash
Benjamin Graham lived through the 1929 stock market crash as a working investor, and the experience shaped everything he wrote afterward. Rather than treating the crash as proof that stocks were simply too risky, Graham set out to build a more rigorous, evidence-based discipline for figuring out what a security was actually worth — separate from whatever the market's mood happened to be on a given day.
"Security Analysis" and the birth of a discipline
In 1934, Graham and his Columbia colleague David Dodd published "Security Analysis," a dense, technical work that's still considered the founding text of value investing. Its core argument was that a stock has an underlying, calculable value based on the business's assets, earnings, and financial strength, and that a careful investor's job is to estimate that value independently and only buy when the market price sits meaningfully below it. Graham followed it in 1949 with "The Intelligent Investor," a more accessible book aimed at individual investors, which Warren Buffett has repeatedly called the best book on investing ever written.
Margin of safety: Graham's central idea
If there's one concept most associated with Graham, it's margin of safety — the practice of only buying a security when its price is low enough, relative to your estimate of its true worth, to absorb the possibility that your estimate is wrong, or that something unexpected goes wrong with the business. Graham illustrated the idea with a simple analogy: you don't need to know a truck's exact weight to know it's safe to drive over a bridge rated for 10,000 pounds if the truck only weighs 4,000.
- Estimate a business's intrinsic value conservatively, using tangible assets and demonstrated earnings power rather than speculative growth projections.
- Only buy with a meaningful discount, or margin of safety, between that estimate and the market price.
- Diversify across many such opportunities, since even careful analysis will sometimes be wrong about any single company.
Mr. Market: a metaphor that outlived the man
Graham personified the stock market's daily mood swings as a character he called "Mr. Market" — an emotional business partner who shows up every day offering to buy your shares or sell you his at a different, often irrational, price. Graham's point was that Mr. Market is there to serve you, not to guide you: you're free to ignore his manic price swings entirely, or take advantage of them when they're clearly wrong, but never obligated to accept his mood as a verdict on what your investment is actually worth.
Graham's advice wasn't to predict the market's next move. It was to build a process sound enough that you didn't need to.
The teacher behind the most famous student
Graham taught investing at Columbia Business School for over two decades, and among his students was a young Warren Buffett, who later worked directly for Graham's investment partnership after graduating. Buffett has credited Graham's framework, particularly margin of safety and the Mr. Market metaphor, as the foundation of his own approach, even as Buffett and Charlie Munger later expanded on Graham's stricter, asset-focused style to place more weight on business quality and durable competitive advantages.
This article is educational and general in nature. It isn’t personalized investment, tax, or legal advice — always weigh your own circumstances, or talk to a licensed professional, before making financial decisions.
Keep reading
Related guides on this topic.
Walter Schloss: The Value Investor Who Beat the Market for 45 Years Without Meeting a CEO
Walter Schloss never went to university, worked from a small office and owned dozens of cheap, dull companies — and compounded his investors’ money at about 15% a year for nearly half a century. How he did it.
Legendary InvestorsPeter Cundill: The Canadian “Indiana Jones” of Value Investing
Peter Cundill travelled the world looking for companies selling for less than their net assets, and grew $10,000 into more than $900,000 over 36 years. His record, his method and his favourite word: patience.
Legendary InvestorsRadhakishan Damani: The Quiet Investor Who Built DMart and Became a Billionaire
Radhakishan Damani left college after a year, made his name on the Mumbai stock market and then walked away to build DMart, one of India’s most valuable retailers. His story, his investing style, and what ordinary investors can take from it.
Legendary InvestorsJean-Marie Eveillard: The Value Investor Who Refused to Buy the Dot-Com Bubble
A Frenchman in New York, Jean-Marie Eveillard turned $1,000 into nearly $45,000 over 25 years at the SoGen International fund, nearly losing his job along the way for refusing to buy technology shares in 1999. His record and his lessons.
Legendary InvestorsDuan Yongping: The “Chinese Buffett” Who Turned $2 Million in NetEase Into $200 Million
The engineer behind the BBK electronics group retired at 40, moved to the US and became one of China’s most admired investors, buying NetEase near its low, Apple and Tencent. What he did, and what ordinary investors can learn from it.
 Legendary Investors
Francisco García Paramés: The Spanish Value Investor Who Started Again at Cobas
Spain’s best-known fund manager beat the Madrid market by a wide margin for two decades at Bestinver, walked away in 2014, then spent five years underwater at his new firm before his funds came roaring back.