What Is an Economic Moat? The Competitive Advantages That Protect Profits
An economic moat is what stops competitors from taking a company’s profits. The main kinds of moat, how to spot one in a company’s numbers, why moats erode, and why a great moat does not always make a great investment.
Where the idea comes from
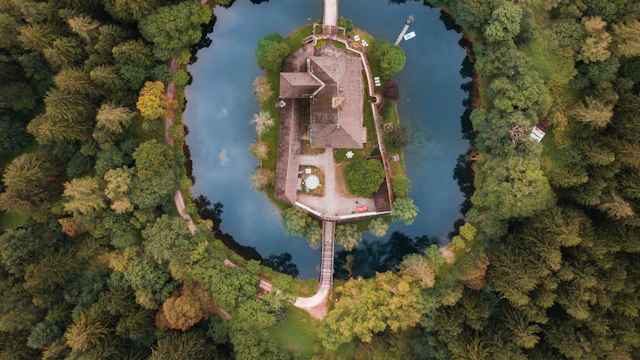
Warren Buffett has long described the businesses he wants to own as economic castles protected by moats. A castle is valuable, but its owner can only keep the treasure inside if invaders cannot get across the water. In business terms, high profits attract competitors; a moat is whatever stops them from taking those profits away. Companies with wide moats can earn high returns on their capital for decades, which is why investors pay so much attention to them.
The main kinds of moat
- Brand: customers will pay more for a name they trust, as with some luxury goods, drinks and consumer products, even when cheaper alternatives exist.
- Network effects: a service becomes more useful as more people use it, as with payment networks, marketplaces and stock exchanges, which makes it hard for newcomers to compete.
- Switching costs: changing supplier is costly, risky or disruptive, as with business software that runs a company’s operations or a bank account with many payments attached.
- Cost advantages: a company can produce more cheaply than rivals thanks to scale, location or processes, and undercut them while staying profitable.
- Intangible assets: patents, licences and regulatory approvals that legally keep competitors out, at least for a time.
Some analysts add efficient scale: a market only big enough for one or two profitable companies, such as an airport or a pipeline in a given area, where a new entrant would struggle to earn a return.
How to spot a moat in the numbers
A moat should show up in a company’s results over many years, not just in its marketing. Signs include a return on capital that stays well above what competitors earn, through good years and bad; the ability to raise prices without losing customers; stable or rising profit margins; and market share that holds steady when rivals attack. A company that needs to spend ever more on advertising or price cuts just to stand still probably does not have one.
A few questions help test whether a moat is real:
- If a well-funded competitor tried to copy this business tomorrow, what would stop it?
- Could the company raise prices by 10% without losing many customers?
- Have its returns on capital stayed high for at least five to ten years, including through a downturn?
A moat is not what a company says about itself. It is what its competitors have failed to do to it.
Moats do not last for ever
Technology can drain a moat surprisingly quickly: newspapers once had local advertising monopolies, and camera film makers had powerful brands, until digital alternatives arrived. Regulation can remove a licence or a patent can expire. Management can also waste an advantage, for example by expanding into businesses where the moat does not apply. That is why investors who focus on moats keep asking whether the advantage is widening or narrowing, not just whether it exists.
A great moat at the wrong price
The market usually knows which companies have strong moats, and their shares often trade at high valuations as a result. Buying an excellent business at a price that already assumes years of perfect results can still lead to poor returns. Investors such as Terry Smith summarise the point in three words: do not overpay.
What it means for ordinary investors
Understanding moats helps you think clearly about any company, and to be sceptical of businesses that grow fast without any protection from competition. But you do not need to find moats yourself to benefit from them. A broad, low-cost index fund owns the companies with the strongest competitive advantages in the market in proportion to their size, without the risk of picking the wrong ones. This guide is general education, not personal financial advice.
Return on equity (ROE) explained
The ratio that often reveals a moat, and the traps that can make it look better than it is.
This article is educational and general in nature. It isn’t personalized investment, tax, or legal advice — always weigh your own circumstances, or talk to a licensed professional, before making financial decisions.
Keep reading
Related guides on this topic.
 Value Investing & Stock Analysis
Return on Equity (ROE) Explained: Formula, Examples and the Traps
Return on equity shows how much profit a company earns on the money its shareholders have put in. How to calculate it, what counts as a good ROE, and why a high number can be a warning sign rather than a strength.
 Legendary Investors
Warren Buffett Steps Down as Berkshire Chairman: What Changes for Shareholders
Warren Buffett stepped down as chairman of Berkshire Hathaway on 18 September 2026. Who runs the company now, what actually changes for shareholders, and what stays exactly the same.
 Legendary Investors
Warren Buffett: Investment Philosophy and Track Record
From a Nebraska newspaper delivery boy to the most closely watched investor alive — here's the philosophy behind Warren Buffett's six-decade track record.
 Value Investing & Stock Analysis
How to Read a Company's Balance Sheet
A balance sheet is a snapshot of what a company owns, owes, and is worth on a single day. Here's how to read one without an accounting degree.
 Value Investing & Stock Analysis
How to Read a Quarterly Earnings Report
A company can beat on profit and fall ten percent. Understanding why means looking past the headline number to expectations, guidance, and the cash-flow statement underneath.
 Value Investing & Stock Analysis
The P/E Ratio Explained: Is a Stock Overvalued?
One of the most quoted numbers in investing tells you how much you're paying for a dollar of a company's earnings — but it's easy to misread.