Prem Watsa: Fairfax Financial and “Canada’s Warren Buffett”
Prem Watsa arrived in Canada from India with almost nothing, took control of a small trucking insurer in 1985 and built it into Fairfax Financial, a global insurance group run on Buffett-style principles, with some very contrarian bets along the way.
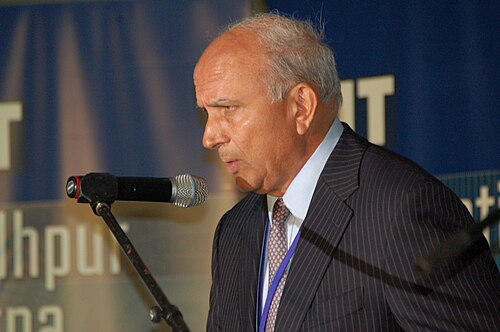
Photo: செல்வா at Tamil Wikipedia · CC BY 3.0, via Wikimedia Commons
From Hyderabad to Toronto
Prem Watsa was born in Hyderabad, India, on 7 August 1950. He graduated in chemical engineering from the Indian Institute of Technology Madras in 1971, then moved to Canada, arriving, according to The Canadian Encyclopedia, with just 8 rupees, and took an MBA at the University of Western Ontario, now the Ivey Business School. He began his investment career in Toronto in 1974 as an analyst at Confederation Life, and in 1984 co-founded the investment firm Hamblin Watsa Investment Counsel.
In 1985 he took control of Markel Financial, a struggling Canadian trucking insurer, and in 1987 renamed it Fairfax Financial Holdings, a name drawn from “fair and friendly acquisitions”.
The Berkshire model, Canadian style
Watsa has openly modelled Fairfax on Warren Buffett’s Berkshire Hathaway, which is why he is often called “Canada’s Warren Buffett”. The idea is simple. Insurance companies collect premiums upfront and pay claims later, and in between they can invest that money, known as the float. If the insurance business is run carefully, the float costs little or nothing, and good investment returns flow to shareholders. Fairfax grew by buying insurance companies around the world, and its annual premiums reached about $10 billion by 2014. Its long-stated aim has been to grow book value per share by about 15% a year over the long term, the same yardstick Buffett used for decades.
- Long-term value investing, with a willingness to sit in cash or government bonds when prices look too high.
- Decentralised management, with insurance subsidiaries run largely by their own teams.
- Protecting against disaster first, through hedges and defensive positions when risks look underpriced.
- Friendly acquisitions rather than hostile takeovers.
The 2008 call
From around 2005, while many financial companies piled into US mortgage-related securities, Watsa kept much of Fairfax’s money in safe, low-yielding government bonds and bought protection against a credit crisis, including credit default swaps, which pay out when borrowers default. When the US housing market collapsed, those positions paid off handsomely. 2008 was Fairfax’s most profitable year up to then, with net earnings of $1.47 billion, and the gains gave it money to invest when prices were low.
Watsa’s best results came from being cautious when others were greedy; his costliest mistakes came when that caution lasted too long.
When contrarian goes wrong
Not every call worked. After 2008 Watsa worried about a long period of deflation and hedged Fairfax heavily against falling share prices. As markets rose through the 2010s, those hedges cost the company dearly, and he removed them at the end of 2016.
He also became closely involved with BlackBerry, joining the board of its predecessor, Research In Motion, in 2012. In 2013 Fairfax led a $4.7 billion offer to take BlackBerry private; the deal fell through, and Fairfax invested in the company’s convertible bonds instead. BlackBerry never regained its place in phones and became a much smaller software company. Closer to home, Watsa has backed India’s growth through Fairfax India Holdings, a listed company launched in 2015 to invest in Indian businesses. He was made a Member of the Order of Canada in 2015.
What investors can learn from Watsa
Fairfax’s story shows the power of the insurance-and-investment model when it is run with discipline, and the value of thinking about what could go wrong before thinking about what could go right. It also shows the cost of being early, or wrong, on big economic calls. For most investors, the transferable part is the first one: protect against large losses, keep some money in safe assets, and be ready to buy when others are forced to sell. This profile is general education, not a recommendation to buy any share.
Warren Buffett’s investment philosophy, explained
How Berkshire Hathaway uses insurance float, the model Fairfax was built on.
This article is educational and general in nature. It isn’t personalized investment, tax, or legal advice — always weigh your own circumstances, or talk to a licensed professional, before making financial decisions.
Keep reading
Related guides on this topic.
Peter Cundill: The Canadian “Indiana Jones” of Value Investing
Peter Cundill travelled the world looking for companies selling for less than their net assets, and grew $10,000 into more than $900,000 over 36 years. His record, his method and his favourite word: patience.
 Legendary Investors
Warren Buffett Steps Down as Berkshire Chairman: What Changes for Shareholders
Warren Buffett stepped down as chairman of Berkshire Hathaway on 18 September 2026. Who runs the company now, what actually changes for shareholders, and what stays exactly the same.
 Legendary Investors
Warren Buffett: Investment Philosophy and Track Record
From a Nebraska newspaper delivery boy to the most closely watched investor alive — here's the philosophy behind Warren Buffett's six-decade track record.
Legendary InvestorsDuan Yongping: The “Chinese Buffett” Who Turned $2 Million in NetEase Into $200 Million
The engineer behind the BBK electronics group retired at 40, moved to the US and became one of China’s most admired investors, buying NetEase near its low, Apple and Tencent. What he did, and what ordinary investors can learn from it.
 Value Investing & Stock Analysis
What Is an Economic Moat? The Competitive Advantages That Protect Profits
An economic moat is what stops competitors from taking a company’s profits. The main kinds of moat, how to spot one in a company’s numbers, why moats erode, and why a great moat does not always make a great investment.
Legendary InvestorsRaamdeo Agrawal: The Co-Founder of Motilal Oswal and His QGLP Approach to Investing
Raamdeo Agrawal arrived in Mumbai to study accountancy, co-founded Motilal Oswal and became one of India’s best-known long-term investors. His QGLP framework, the Hero Honda and Eicher stories, and the lessons for ordinary investors.